A regional headquarters in Saudi Arabia gives a multinational group a base for directing and supporting its regional businesses. The important decision is which functions, people and decision-making authority will actually move to the Kingdom. A registration certificate and an office address cannot, by themselves, establish a functioning headquarters.
An RHQ project needs three connected workstreams: the Ministry of Investment requirements, the operating arrangements between group companies, and the conditions attached to tax incentives. Government-contracting eligibility requires a separate assessment. This guide explains how to bring those workstreams together without treating the RHQ as an unrestricted trading company.
What is an RHQ in Saudi Arabia
MISA describes the RHQ as an entity established by a foreign multinational company to support, manage and strategically direct its branches and subsidiaries in the Middle East and North Africa. Its September 2026 Investor Guide continues to identify an RHQ license category within the current investment-registration framework. References to RHQ licensing therefore remain relevant even though general foreign-investment procedures now use registration terminology. 1
The RHQ should have a defined regional mandate: which companies it serves, which decisions it makes and which activities remain with operating subsidiaries. An organizational chart is useful only when contracts, job descriptions and actual working practices follow it.
RHQ versus an operating company or branch
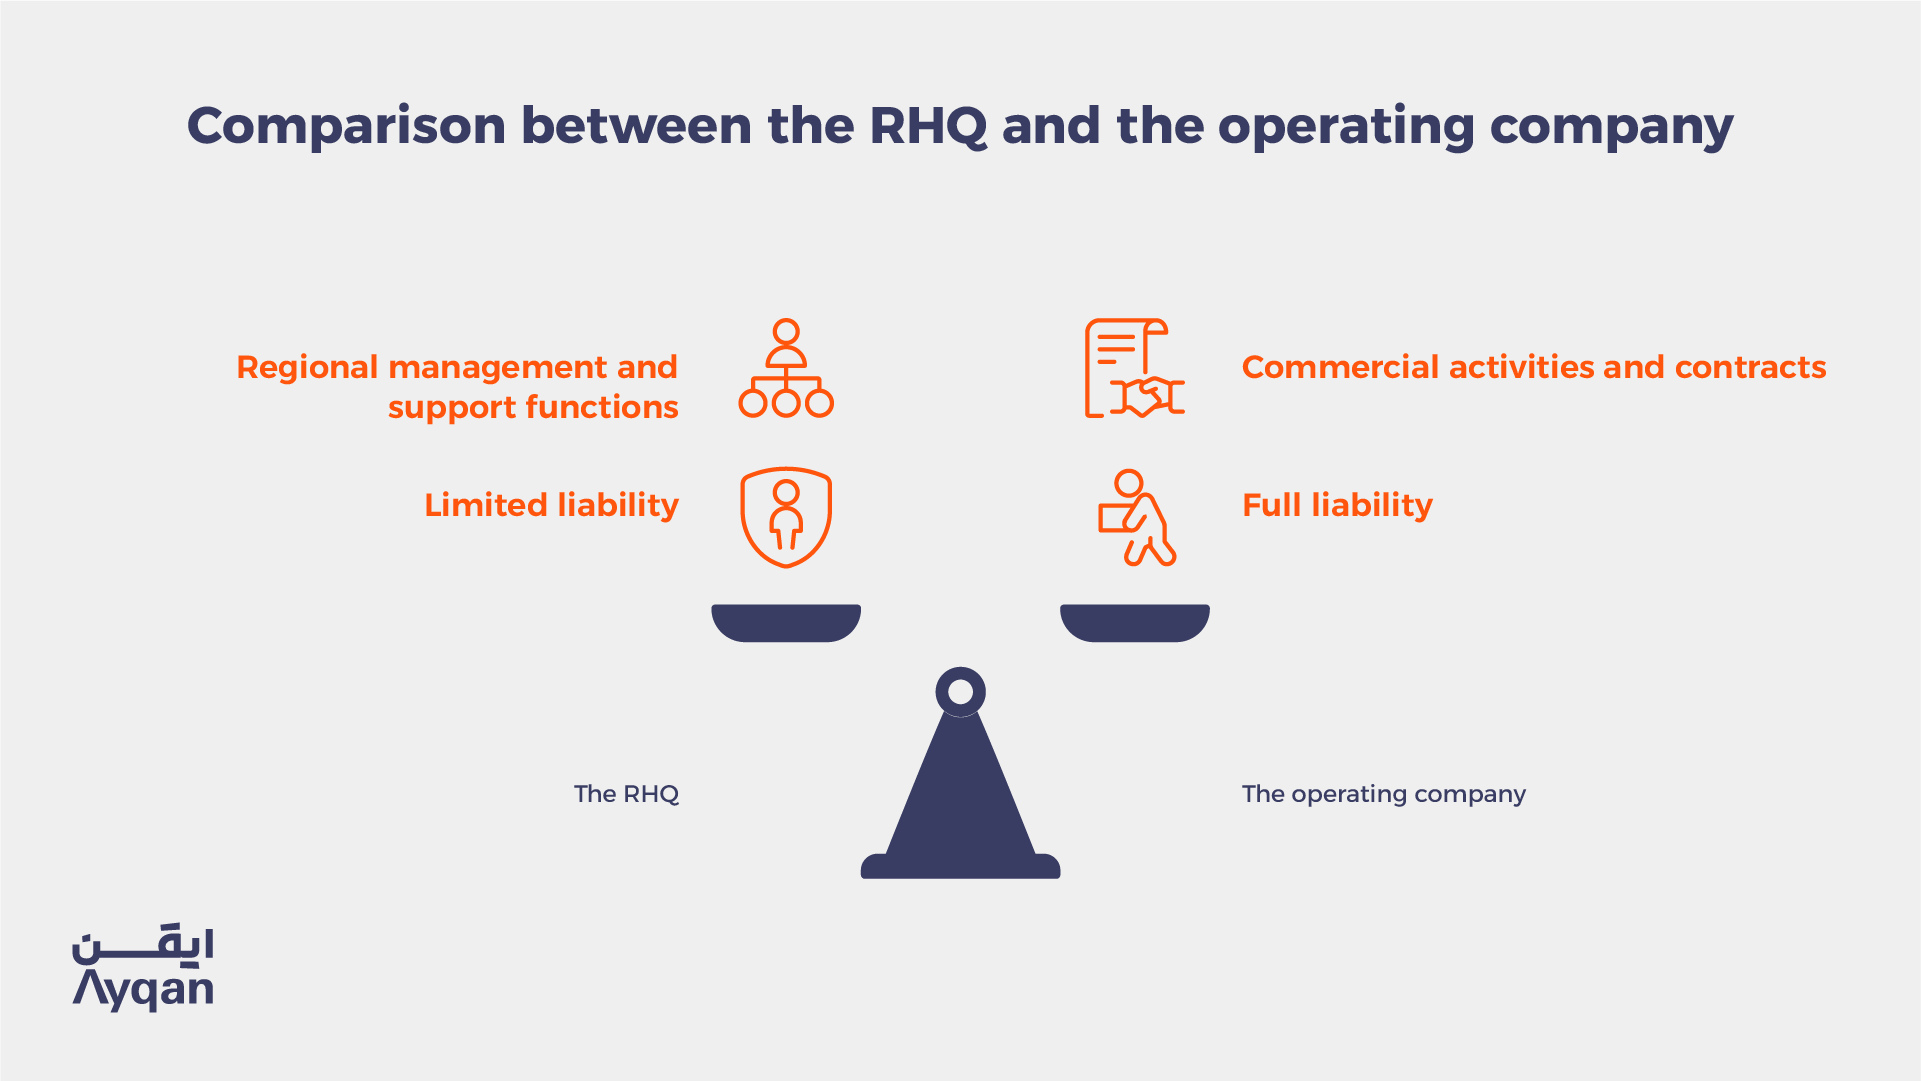
The license purpose and the legal form are separate questions. MISA's guide permits the RHQ to be established through a company or a registered foreign-company branch. Choosing a branch does not make that branch a separate corporation from its parent. Liability, contracting authority and the parent's exposure require their own legal analysis. 1
| Arrangement | Main question to resolve |
|---|---|
| Licensed RHQ | Which approved regional management and support functions will it perform? |
| Saudi operating company | Which licensed commercial activities, customer contracts and delivery obligations belong here? |
| Foreign-company branch | What may the branch undertake, and how does responsibility remain with the foreign parent? |
| Group service agreement | Which services are supplied, to whom, for what charge and with what evidence? |
For the wider incorporation process, see Ayqan's company formation guide. The RHQ analysis adds activity, staffing and substance requirements to that process.
Who should consider an RHQ license
The strongest candidate is an established multinational group that can place genuine regional leadership and support functions in Saudi Arabia. The business case should identify the companies served, the value of centralizing functions and the cost of maintaining the required team.
MISA's published RHQ terms describe a multinational presence in at least two countries outside Saudi Arabia and the group's headquarters country. The September 2026 guide requests two valid commercial registrations of different business entities and the applicant's audited financial statements for the preceding financial year. Confirm how MISA applies the group-presence test to the proposed applicant and ownership chain when preparing the file. 12
A group should not assume that anticipated expansion, an unimplemented structure or an unrelated shareholder's overseas business establishes its eligibility. Map the legal entities and ownership evidence before committing to premises or executive relocations.
Which activities can the RHQ perform
Mandatory regional functions
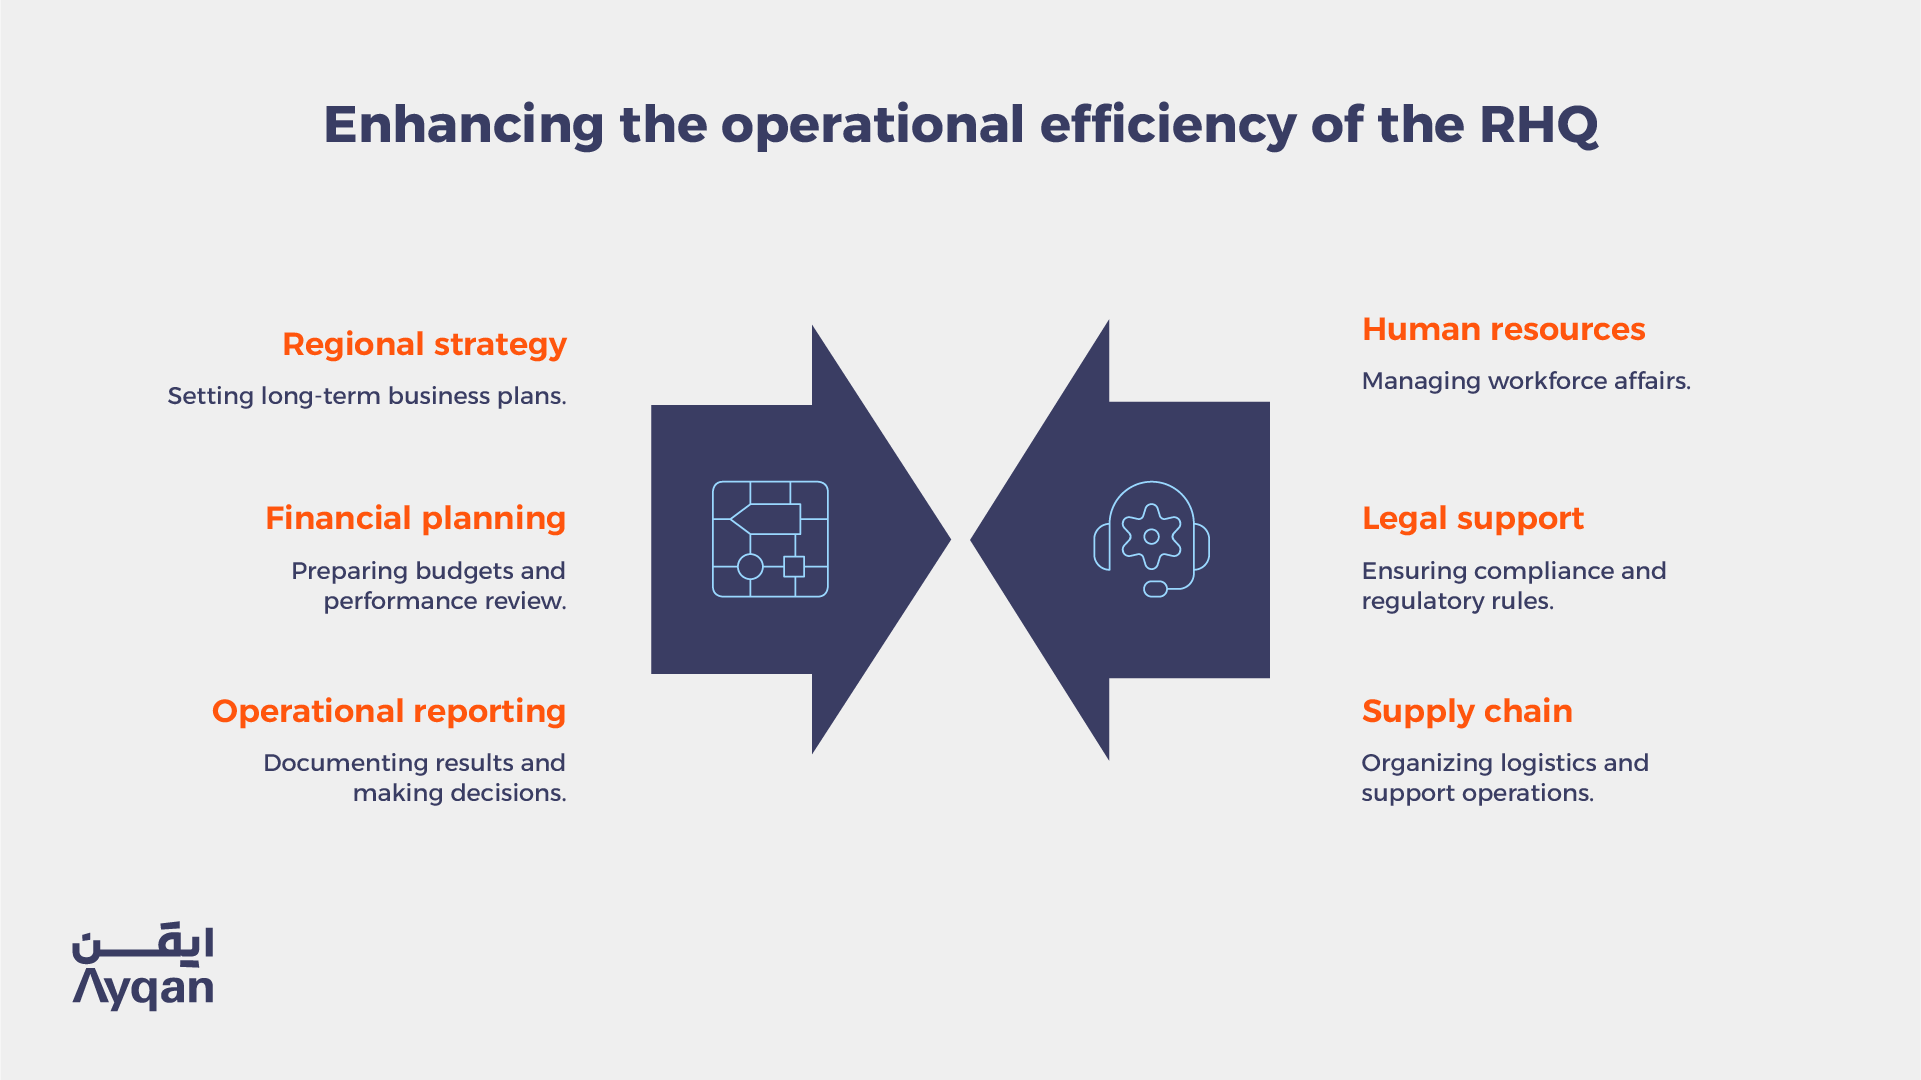
MISA's published terms identify strategic direction and management functions, including regional strategy, business planning, budgeting, performance review and operational reporting. The current guide requires mandatory activities to commence within six months of license issuance. 12
Document who approves regional budgets, receives management reports and has authority to act on the conclusions. A headquarters that forwards instructions from overseas without meaningful local responsibility may struggle to demonstrate its intended role.
Optional activities selected for the application
At least three optional RHQ activities must begin within one year. Published examples include human resources, accounting, compliance, legal support, research, technical assistance and supply-chain management. Select functions the team will actually perform and confirm their permitted scope in the application and issued authorization. An optional activity label does not replace a separate professional or sector license where one is required. 12
Revenue and commercial activity boundaries
MISA restricts direct revenue-generating commercial operations outside licensed RHQ activities. This is not a statement that every RHQ must have no revenue: ZATCA's rules expressly address income from eligible RHQ activities. The service, recipient, charge and actual work must support the classification. 13
For example, a regional budgeting team may provide documented management services to group companies. Selling the group's products to Saudi customers presents a different activity question. Keep customer-facing trading and delivery in the appropriately authorized entity.
Staffing and commencement deadlines
The September 2026 guide identifies the following requirements. Record the starting date against the issued license or registration and the conditions in the approval. 1
| Requirement | Planning implication |
|---|---|
| Mandatory activities within six months | Have the leadership, systems and delegated authority ready to operate. |
| At least three optional activities within one year | Allocate an accountable owner, staff and evidence to each function. |
| At least 15 full-time employees within one year | Build a realistic recruitment and relocation schedule. |
| At least three qualifying senior executives within that team | Match seniority, skills and actual responsibilities to MISA's requirements. |
The guide refers to Executive Director and Vice-President level personnel and relevant experience developed within the group's headquarters or another RHQ. Job titles alone should not be the compliance evidence. Payroll, contracts, reporting lines and records of work should tell a consistent story.
Confirm any RHQ-specific workforce benefits against the entity's approved status. Ordinary employment documentation, work authorization and applicable social-insurance obligations still need attention. Ayqan's Saudization and Nitaqat guide explains why workforce obligations must be assessed by entity and activity.
Preparing the application and implementation file
Start with MISA's current checklist and the applicant's specific circumstances. The September guide calls for valid business-entity registrations and recent audited financial statements, with authentication requirements. Requirements for translations, authorization and foreign documents should be confirmed before submission. 1
A useful working file also contains the group structure, regional mandate, proposed legal form, activity selection, staffing timetable, premises plan and proposed service arrangements. These are practical planning materials; the live application determines the mandatory submission items.
After approval, coordinate incorporation or branch registration, commercial-record requirements, banking, tax registration and employment setup. Assign each action to a named owner. For the underlying investment process, use Ayqan's MISA registration guide.
What the RHQ tax incentives cover
Eligible income and specified withholding payments
ZATCA's RHQ Tax Rules provide a zero-percent income-tax rate on eligible income. They also provide zero-percent withholding tax for specified payments to non-residents: dividends, payments to related persons, and payments to unrelated persons for services necessary for RHQ activities. Payments connected with non-eligible activities and avoidance arrangements do not receive that withholding treatment. 3, Article 3
The incentives apply to the qualifying RHQ. They do not automatically exempt other group companies, all Saudi revenue or every outbound payment. An RHQ license also does not create a general VAT exemption. Assess each tax under its applicable rules; see Ayqan's VAT compliance guide.
Duration and continuing conditions
The rules provide a 30-year incentive period, subject to renewal, commencing when the RHQ obtains its license for eligible activities and ending earlier if it ceases to qualify as an RHQ. Continued eligibility, economic substance and compliance remain essential throughout that period. 3, Article 4
Economic substance must be demonstrated in practice
Article 5 of the tax rules requires a valid license, suitable premises, management and direction in Saudi Arabia, appropriate local operating expenditure, eligible-activity revenue, at least one resident director, and sufficient qualified full-time personnel. The rules specifically address board meetings where strategic decisions are made. 3
Translate those requirements into evidence: board and management records, local approvals, employment files, office arrangements, service outputs, invoices and financial records. Holding meetings in Riyadh while all substantive decisions remain elsewhere does not resolve the management-and-direction question.
MISA's numerical staffing requirements and ZATCA's substance test must both be considered. A team can meet a minimum headcount while still being inadequate for the scale of the functions it claims to perform.
Intercompany agreements and transfer pricing
The tax rules require related-party transactions to follow the arm's-length principle. Prepare service agreements that identify the beneficiaries, scope, responsibilities, charging methodology and allocation of shared costs. Retain evidence that the services were delivered and benefited the recipient. 3, Article 12
Tax rules requiring separate accounts for non-eligible activities do not authorize an RHQ to conduct activities prohibited by its license. A proposed new revenue stream therefore needs both a licensing assessment and a tax assessment before it begins.
Government contracting requires a separate eligibility check
Saudi government-contracting controls address companies without an RHQ in the Kingdom and specified related parties. Their definitions, procurement procedures and exceptions matter; the framework should not be reduced to a universal statement that every foreign supplier must establish an RHQ for every contract. 4
Before bidding, identify the purchasing authority, the bidder, the relevant group company and any distributor or supplier relationship. Check the controls applicable to that procurement, the current tender documents and any required exception approval. The published controls distinguish public competitions, limited competitions and direct contracting, and provide defined exceptions.
An RHQ approval is not a promise of a government award. It also does not replace the operating entity's authority to supply the goods or services, sector approvals or tender qualification requirements.
Ongoing reporting and the cost of non-compliance
ZATCA requires applicable tax and zakat returns, an annual economic-substance report and accounts for each tax year, including the initial partial year. The RHQ must also maintain the current MISA record and meet the updates and conditions attached to its authorization. 13, Articles 6–9
For substance failures, Article 11 establishes a notice and correction process, followed by escalating penalties and possible suspension of incentives. Deliberate misuse can lead to revocation and tax reassessment under Article 12. Build a calendar covering license conditions, financial reporting, substance evidence, staff changes and intra-group transactions; do not wait for an inspection to assemble the records.
A practical RHQ readiness checklist
Confirm the qualifying group structure and documentary evidence with MISA.
Define the regional mandate, companies served and actual decision rights.
Separate RHQ activities from trading, delivery and regulated professional services.
Select optional functions that can be operational within the required period.
Secure suitable premises and a credible staffing and relocation plan.
Document service arrangements, transfer pricing and the supporting evidence.
Assess tax incentives, substance and government-contracting eligibility separately.
Assign responsibility for commencement milestones and recurring compliance.
When legal review may be useful
An RHQ project can involve licensing, corporate structuring, intercompany agreements, employment arrangements, tax substance and procurement eligibility at the same time. A coordinated review may be useful before the operating model, staffing plan and group service arrangements are finalized. Ayqan’s regional investment and corporate practice supports businesses assessing these connected issues.
Official sources
Ministry of Investment, Investor Guide, 13th Edition 03–2026, sections 5.1.2 and 5.1.3: English and Arabic.
Ministry of Investment, published RHQ terms and conditions. Read alongside the current guide and issued authorization.
ZATCA, Regional Headquarters Tax Rules, Board Resolution 9-1-24 of 4 February 2024, particularly Articles 3–14.
Umm Al-Qura, government-contracting controls for companies without a regional headquarters and related parties, published 6 January 2023. Check subsequent decisions and the rules applicable to the particular procurement.
Legal notice
This article provides general information based on the sources checked on the date above. It is not advice on a particular structure, tax position or procurement. Application requirements and the conditions in the relevant authorization must be checked for each case.